[FIN]CROSS-BORDERVOL: $4.2T
[SEC]CYBER ALERT: TIER2
[POL]IS0 GROWTH:+14%
[GEO] CLOUDINDEX: +2.4%
Structural Logic
Category Filters
Apple Pay and Google Pay Officially Launch in Uzbekistan
Lead Author
Published
Views:
Apple Pay and Google Pay officially launched in Uzbekistan on October 27, 2026, according to the supplied event summary, allowing local bank customers to link cards to the two international mobile wallets. The development expands digital payment options and signals closer alignment of the country's payment infrastructure with international standards. From an industry perspective, banks, merchants and payment service providers may need to review service eligibility, acceptance arrangements and customer support, although the supplied information identifies no specific regulatory amendment or new compliance obligation.
Local Bank Customers Gain Access to Two International Wallets
The supplied information states that Apple Pay and Google Pay became available in Uzbekistan on October 27, 2026. Local bank customers can now link their cards to these wallets, adding to the digital payment choices available to consumers and merchants.
The event summary describes the launch as a further step toward aligning Uzbekistan's payment infrastructure with international standards and supporting the transition toward cashless payments.
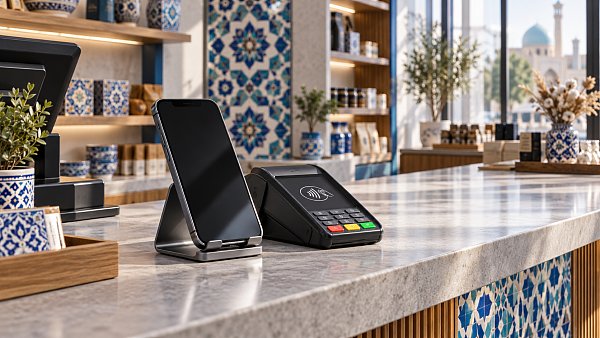
Payment Providers and Merchants Face Different Implementation Questions
Card linking puts bank service coverage in focus
Analysis suggests that banks may face additional questions about which cards and customer accounts can use the wallets. The supplied information does not identify participating banks, eligible card categories or service conditions. Banks assessing the practical implications could review their own confirmed service scope and ensure that customer communications accurately describe availability.
Merchant acceptance needs separate verification
For merchants, the potential benefit is a broader choice of payment methods for customers. However, the launch announcement alone does not establish that every merchant can accept payments through both wallets. From an operational perspective, merchants may need to check acceptance arrangements with their payment providers before changing checkout instructions or advertising wallet support.
Integration and equipment decisions may require clearer specifications
Analysis suggests that payment service providers and equipment integrators could receive requests to assess existing checkout arrangements. Any resulting procurement or delivery decisions would depend on verified compatibility and service requirements. The supplied summary provides no basis for assuming that equipment replacement, additional certification or a particular technical upgrade is required.
Verify Service Conditions Before Changing Payment Operations
Confirm the scope of card and wallet availability
Businesses considering operational changes should first seek confirmation of the cards, accounts and services covered by the launch. This is a practical recommendation rather than a stated requirement. The general availability described in the supplied summary should not be treated as confirmation that every customer or card is eligible.
Check acceptance before committing procurement budgets
Merchants and integration providers could assess whether their existing payment arrangements support the intended customer experience. Where purchases or service changes are being considered, it would be reasonable to request documented compatibility information and agreed delivery conditions from suppliers. No procurement deadline or mandatory replacement programme is specified in the input.
Separate platform conditions from legal obligations
From a compliance perspective, businesses should distinguish any subsequently confirmed wallet or provider conditions from requirements imposed by law or regulation. The supplied information does not identify a new licence, certification scheme, legal instrument or binding implementation timetable. Any claim that the launch creates such obligations would require additional evidence.
Prepare customer support around verified capabilities
As an operational recommendation, banks and merchants could review how they explain card linking, payment availability and service problems to customers. Support materials should reflect confirmed capabilities. Any assumptions about transaction handling or responsibility for resolving problems would need validation with the relevant service providers.
A Service Launch Signals Integration, While Formal Rule Changes Remain Unspecified
At this stage, it is more appropriate to understand the event as an implemented expansion of payment services, as described in the supplied summary, and a signal of further international payment integration. It does not, on the available information, establish the adoption of a particular technical standard or a change in financial regulation.
Editorial analysis suggests that the significance for businesses will depend on how broadly the services become usable in practice. Confirmed participation, merchant acceptance conditions and customer experience would help determine whether the additional payment options translate into operational benefits. These remain matters for observation rather than established outcomes.
Business Decisions Should Follow Confirmed Availability
The launch adds international mobile wallet options to Uzbekistan's payment market. Analysis suggests that its practical value for individual businesses will depend on verified service coverage and compatibility with their payment arrangements. A measured response is to assess relevant services, validate any proposed procurement or integration changes, and update customer communications as implementation details become clear. The supplied information supports recognition of a service launch, while broader compliance and commercial conclusions require further evidence.
Basis of This Report and Details Still to Verify
This article is based solely on the user-provided news title, event date and event summary. Statements about potential business effects and recommended actions are analysis, rather than additional confirmed facts.
No specific official source links were provided in the input, and further verification remains necessary. Relevant materials for subsequent checks could include official launch announcements, participating banks' service notices, payment providers' acceptance documentation and any applicable regulatory publications. Continued attention should focus on confirmed service coverage, implementation conditions, any subsequently published compliance requirements, and feedback from businesses and customers.
Tags
Recommended for You
 OpenRouter Removes Three AI Inference Providers Over Prompt Theft RisksOpenRouter removes three AI inference providers over prompt theft risks and changes zero data retention eligibility for 125 endpoints. Explore what buyers need to know.Nov 22, 2026Lina Cloud
 FBI Database Suspected Breached; USDA Payment System Disrupted by CyberattackFBI database breach suspected as a USDA cyberattack disrupts farm payments. Explore the potential business impact and practical steps amid uncertainty.Nov 21, 2026Lina Cloud
 How to choose the right capacity for wholesale commercial planetary mixersPlanetary mixer wholesale commercial buyers: learn how to match capacity to recipes, compare supplier ratings, and choose the right mixer with confidence.Nov 21, 2026Lina Cloud
 European Commission Confirms AI-Enabled Cyberattack Took Applications OfflineEuropean Commission AI-enabled cyberattack took several applications offline. Discover what is known about the disruption, ARTEX and the ongoing investigation.Nov 20, 2026Lina Cloud
 When should OEMs conduct electromagnetic compatibility testing?Electromagnetic compatibility testing: OEM teams can reduce redesign risks by testing prototypes early and assessing release-ready products. Discover when to test.Nov 20, 2026Marcus Trust
 CISA Adds Four Vulnerabilities to Known Exploited Vulnerabilities CatalogCISA adds four vulnerabilities to its Known Exploited Vulnerabilities catalog. Discover what the listings mean for patch priorities and risk management.Nov 19, 2026Lina Cloud
 Can IP65 LED grow lights withstand routine washdowns?Can IP65 LED grow lights handle routine washdowns? Discover what the rating covers and how to clean fixtures safely without risking damage.Nov 19, 2026Marcus Trust
 Equinor Reports Cyberattack on IT Systems; Oil and Gas Production UnaffectedEquinor reports a cyberattack on its IT systems, with oil and gas production unaffected. Explore what the incident means for energy supply.Nov 18, 2026Lina Cloud
 How to assess integration capabilities when choosing AI kiosk suppliersCompare AI kiosk suppliers with a practical integration checklist covering APIs, payments, identity, peripherals, failure recovery, and support.Nov 18, 2026Dr. Hideo Tanaka
 US States and Cities Move to Ban Crypto Kiosks Amid Rising FraudUS crypto kiosk bans are gaining momentum amid rising fraud. Discover what local restrictions could mean for operators, suppliers and deployment plans.Nov 17, 2026Dr. Hideo Tanaka
 How many touch points does a classroom interactive panel need?Interactive panel touch points for classroom use: discover when 10 or 20 points make sense and how to choose a reliable display for student collaboration.Nov 17, 2026Professor Sarah Ed
 How to verify component distributors on a supplier discovery platformSupplier Discovery Platform tips for verifying component distributors: check authorization, traceability and delivery claims before you buy.Nov 16, 2026Lina Cloud
 Vietnam Health Ministry Orders Stronger Protection of HIV Patient InformationVietnam HIV patient privacy is in focus as the Health Ministry orders stronger data protection. Discover what the instruction means for healthcare providers.Nov 15, 2026Lina Cloud
 How long do Android smart terminals receive security updates?Android smart terminals have varying security update lifespans. Learn how to verify vendor commitments, assess remaining support, and plan a secure deployment.Nov 15, 2026Lina Cloud
 Microsoft 365 Consumer Services Restored After Global OutageMicrosoft 365 consumer services are back after a global outage. Discover what caused the disruption and why enterprise services remain under monitoring.Nov 14, 2026Lina Cloud
 How much does aeration add to aquaculture utility costs?Aquaculture utilities cost can rise significantly with aeration. Learn how to calculate energy expenses, compare equipment, and build a reliable budget.Nov 14, 2026Lina Cloud
 Trump AI Task Force Discusses Cyberattack Reporting Standards for Critical InfrastructureAI cyberattack reporting standards are under discussion for critical infrastructure. Explore potential impacts on operators, suppliers and incident response.Nov 13, 2026Lina Cloud
 How to check an EMC laboratory's test frequency rangeVerify an EMC test frequency range laboratory claim with confidence. Learn how to check accredited scope, test methods, facilities, and product requirements before booking.Nov 13, 2026Marcus Trust
 Singapore PDPC and CSA Issue Joint Advisory on Insecure API Data Protection RisksSingapore PDPC and CSA highlight insecure API data protection risks. Discover what developers and API users should know about security and compliance.Nov 12, 2026Lina Cloud
 How to size industrial coffee processing machinery for your production volumeSize industrial coffee processing machinery with confidence. Learn to calculate throughput, account for losses, and compare supplier capacity claims.Nov 12, 2026Lina Cloud
 Singapore CSA Issues Alert on Microsoft's November 2026 Security PatchesSingapore CSA’s November 2026 Microsoft security patch alert highlights potential risks. Explore what businesses should verify and how to plan updates.Nov 11, 2026Lina Cloud
 How many nits does a digital signage window display need?Explore digital signage brightness nits data for your window display, from shaded storefronts to direct sunlight, and choose a screen that stays readable.Nov 11, 2026Digital Signage
 CISA Adds SonicWall SonicOS MFA Bypass Flaw to KEV CatalogCISA adds the SonicWall SonicOS MFA bypass flaw, CVE-2026-19868, to its KEV catalog. Learn why it matters and what affected organizations should do next.Nov 10, 2026Lina Cloud
 Is a 50 kg spiral dough mixer right for your batch size?Is a 50 kg spiral dough mixer right for your bakery? Compare batch capacity, dough requirements and production timing before you buy.Nov 10, 2026Lina Cloud
 New Zealand NCSC Report Warns AI Is Accelerating CybercrimeNew Zealand's NCSC warns that AI is accelerating cybercrime. Discover what the report means for supply chain security and how organizations can respond.Nov 09, 2026Lina Cloud
 How to choose a touchscreen medical kiosk for patient check-inChoose a touchscreen medical kiosk with confidence. Explore accessibility, integration, privacy, cleaning and costs to find the right patient check-in solution.Nov 09, 2026Dr. Hideo Tanaka
 India’s DPDP Act and Rules Set New Compliance Demands for Schools and EdTechIndia’s DPDP Act and 2025 Rules raise data privacy questions for schools and EdTech. Explore consent, data minimization and practical review priorities.Nov 08, 2026Marcus Trust
 How much horsepower do commercial towable stump grinders need?Choosing towable stump grinders for commercial work? Compare horsepower ranges, cutting performance and towing limits to find the right machine for your workload.Nov 08, 2026Lina Cloud
 US Agencies Warn of Attacks Targeting Food and Medical Cold-Chain SystemsCold-chain cybersecurity is under scrutiny as US agencies warn of attacks on food and medical refrigeration controls. Explore the risks and practical steps to protect supplies.Nov 07, 2026Lina Cloud
 How to verify boric acid purity when buying wholesale from a factoryChoosing a wholesale boric acid factory? Learn how to verify purity, check batch COAs and plan independent tests before placing your order.Nov 07, 2026Marcus Trust
 Class A vs. Class B marine AIS transponders: Which do you need?Choose the right AIS transponder system marine applications demand. Compare Class A, Class B CSTDMA and SOTDMA, plus installation and compliance needs.Nov 06, 2026Lina Cloud
 OpenSSH 10.6p2 Fixes CVE-2026-123158 Password Authentication BypassOpenSSH 10.6p2 fixes CVE-2026-123158, a password authentication bypass. Find out which Linux systems are affected and how to secure them.Nov 06, 2026Lina Cloud
 Is a mini rice harvester for small farms worth the cost?Is a mini rice harvester for small farms worth the cost? Compare ownership expenses, payback, field suitability, and rental options before you invest.Nov 05, 2026Lina Cloud
 CISA Adds WordPress Core RCE Vulnerability to KEV CatalogWordPress core RCE vulnerability CVE-2026-119977 joins CISA's KEV catalog. Explore the active exploitation risk and what WordPress operators need to know.Nov 05, 2026Lina Cloud
 How to verify the EGCG content of 98% green tea extractGreen tea extract 98 EGCG: Learn how to verify purity with HPLC testing, assess COAs, compare reporting bases, and make confident quality decisions.Nov 04, 2026Marcus Trust
 European Supermarkets Hit by Second Wave of Smart Freezer CyberattacksEuropean supermarket cyberattacks target smart freezer controls, raising food safety concerns. Discover what happened and how retailers are responding.Nov 04, 2026Lina Cloud
 How do payment app encryption layers protect card data?Discover how payment app encryption layers protect card data in transit and at rest, and learn what to check when evaluating security and PCI DSS compliance.Nov 03, 2026Lina Cloud
 How to verify the purity of wholesale xylitol sweetenerVerify xylitol sweetener wholesale sugar substitute purity with batch-specific COAs, appropriate lab tests, and sampling practices that help reduce supply-chain risk.Nov 02, 2026Marcus Trust
 Thailand to Require Social Media Platforms to Verify Advertisers From November 1Thailand advertiser verification rules take effect November 1, 2026. Discover what social media platforms and businesses need to know before running paid ads.Nov 02, 2026Marcus Trust
 How does plant capacity affect blood meal processing plant cost?Blood meal processing plant cost depends on capacity, supply, and energy use. Compare plant sizes and uncover ways to improve your investment.Nov 01, 2026Lina Cloud