[FIN]CROSS-BORDERVOL: $4.2T
[SEC]CYBER ALERT: TIER2
[POL]IS0 GROWTH:+14%
[GEO] CLOUDINDEX: +2.4%
Structural Logic
Category Filters
What Financial Infrastructure Supports International Tuition Payments?
Lead Author
Published
Views:
International tuition payments need more than a gateway that accepts money from overseas. They require a connected financial infrastructure: collection accounts and payment rails, foreign exchange services, regulated payment processing, compliance controls, settlement arrangements, and reconciliation linked to student records. The decisive question is whether a payment can move from a family’s account to the correct tuition balance with a clear audit trail and a predictable final amount.
A system can process transactions successfully yet still fail operationally. Funds may arrive without a usable student reference, intermediary charges may create a shortfall, or a payment confirmation may be mistaken for settled cash. Reliable infrastructure must manage both the movement of money and the information needed to recognize, allocate, investigate, and return it.
Map the payment journey before choosing the platform
Start with the institution’s actual collection requirements: where students pay from, which currencies they use, the currency in which tuition is billed, and the accounts into which funds must settle. A university collecting one billing currency from several countries has different requirements from an education group operating campuses with separate legal entities and bank accounts.
The payment journey contains distinct events: the student receives an invoice, a payer selects a method, funds are initiated, the payment is confirmed, money settles, and the tuition ledger is updated. These events should not be compressed into a single “paid” status. A card authorization, an initiated bank transfer, and settled funds represent different levels of certainty.
A useful design connects each event to a stable payment identifier, student identifier, invoice reference, amount, currency, and timestamp. It must also distinguish the student from the payer. Tuition may be funded by a parent, employer, sponsor, or scholarship organization; assuming that the account holder’s name will match the student’s creates avoidable exceptions.
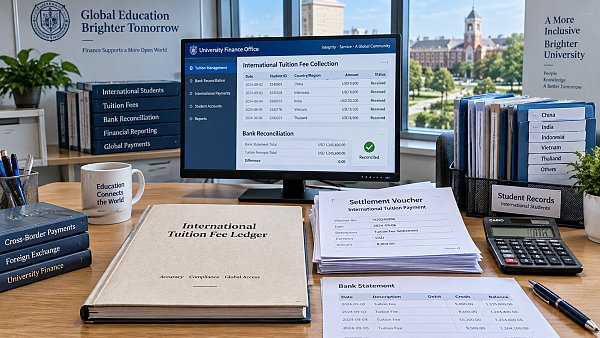
This mapping exposes responsibility gaps. The institution should know which party collects funds, performs conversion, conducts required checks, holds money before settlement, and sends transaction data back to its systems. A single portal can conceal several underlying banks and payment providers.
Choose collection rails by corridor, not by the number of payment options
Cross-border bank transfers remain one route, but they are not the only infrastructure available. A payment provider may offer local bank collection in the payer’s country, then arrange conversion and settlement to the institution. Card networks and supported wallets provide additional routes, subject to transaction limits, acceptance rules, and cost.
SWIFT is a financial messaging network, not a guarantee of immediate or deduction-free settlement. The underlying transfer depends on participating banks, account relationships, applicable checks, and the payment route. Domestic rails also differ: support for a local transfer method does not automatically mean instant availability or unrestricted transaction values.
Evaluate each important country-to-currency corridor separately. Confirm whether the proposed method supports the expected tuition amount, whether the payer can access it, and whether local foreign exchange rules require supporting documents. A long list of accepted methods has little value if the relevant route cannot handle a semester’s payment.
Collection accounts need particular scrutiny. Dedicated accounts or virtual account identifiers can improve attribution, but their legal and operational structures vary. Establish who owns the underlying account, how incoming funds are assigned, and what happens when a payer omits or changes the reference.
Make the exchange rate and final tuition amount explicit
Foreign exchange infrastructure determines more than the displayed rate. It determines when the rate becomes binding, how long a quote remains valid, who bears market movement, and what happens if funds arrive late or in the wrong amount.
Suppose an invoice requires 20,000 units of the institution’s billing currency. The payer needs a clearly stated amount in their chosen currency and an explanation of whether that payment will fully discharge the invoice. A “no transfer fee” claim is insufficient: costs may sit in the exchange-rate spread, bank charges, processing charges, or receiving-account deductions.
Compare proposals using the total payer outlay and the institution’s net receipt for the same corridor and quote time. Separate disclosed payment fees from the exchange-rate margin where the provider makes that information available. This creates a more useful comparison than a headline fee alone.
Quote expiry and underpayment rules belong in the workflow. If a transfer reaches the provider after the quoted rate expires, the system needs a defined recalculation or exception process. Overpayments also require controls: retaining an excess balance, applying it to another invoice, or refunding it should follow an agreed institutional policy rather than an automatic assumption.
Collection currency and settlement currency should be treated separately. Offering families local-currency payment does not mean the institution must maintain accounts in every payer currency. However, conversion and settlement obligations must be contractually clear, including responsibility for any shortfall.
Verify the regulated money flow and the protection of funds
The platform’s brand is not enough to establish its authority to handle tuition money. Verify the contracting legal entity, the entities receiving funds in relevant countries, their regulatory permissions, and the banks or licensed partners supporting the service. Permissions are jurisdiction-specific; authorization in one market does not establish unrestricted coverage elsewhere.
Ask how funds are protected between collection and institutional settlement. Depending on the provider’s structure and local law, arrangements may involve safeguarding, segregated accounts, trust structures, or other protections. Safeguarding is not equivalent to deposit insurance, and neither should be inferred from a statement that the provider “works with regulated banks.”
The review should establish what happens if the provider fails, a partner bank freezes an account, or a corridor becomes unavailable. Contractual settlement promises matter, but so do the legal status of funds and access to transaction records. Obtain a documented explanation of the relevant arrangements rather than relying on a general security statement.
Compliance checks also affect the payment experience. Customer identification, sanctions screening, anti-money-laundering controls, and source-of-funds enquiries may apply according to jurisdiction, payment method, and risk. Third-party tuition payments need a process that records the relationship between payer and student without treating every name mismatch as evidence of wrongdoing.
Responsibilities should be allocated explicitly. The institution needs to know which checks the provider performs, what information it must supply, when additional documents may be requested, and how a held payment is escalated. A payment deadline does not override a legally required review.
Connect reconciliation to student and accounting records
Reconciliation is where a payment service becomes usable tuition infrastructure. Receiving cash in a bank account is not enough; the institution must determine which student balance it reduces, whether the full amount arrived, and how fees and adjustments should be recorded.
A suitable integration links the payment platform with the student information system and finance ledger. Depending on the existing environment, this may use APIs, signed event notifications, scheduled files, or a combination. Real-time integration is valuable only when status definitions and failure handling are reliable.
Require transaction-level records containing the original payment identifier, invoice reference, payer details where appropriate, gross amount, fees, exchange information, net settlement, and settlement batch reference. If one bank deposit represents hundreds of payments, the supporting data must explain the composition of that deposit.
Event handling needs safeguards against duplicate posting. A repeated notification should not credit tuition twice, and a missed notification should be recoverable through a query or reconciliation file. Systems should preserve changes of status rather than overwrite the history, particularly for refunds, reversals, and chargebacks.
Exception handling deserves its own test cases: partial payments, payments covering multiple invoices, duplicate transfers, unknown references, and amounts arriving after an invoice is cancelled. An unmatched payment should enter a controlled review queue, not disappear into an unexplained suspense balance.
Define which status permits each institutional action. A provisional payment acknowledgement may support a temporary deadline extension, while financial clearance may require settled funds. Even settlement does not remove every reversal risk; card disputes and certain bank-payment returns require method-specific treatment.
Design refunds and security into the same infrastructure
Refund capability should be assessed before collection begins. Withdrawals, visa refusals, duplicate payments, and excess balances can all require money to move back across borders. Confirm supported refund routes, processing charges, required approvals, and the information needed to locate the original transaction.
Refunds should generally return through the original payment route to the original payer where feasible and permitted. Requests to send money to a different person or unrelated account need additional scrutiny. The system should link every refund to the original payment and record its effect on the student ledger.
Currency changes can complicate expectations. If tuition is accounted for in the institution’s currency but returned in the payer’s currency, exchange-rate movement and fees may alter the amount received. Refund terms should explain the calculation basis; an exact return of the original local-currency amount should not be promised unless the arrangement supports it.
Security controls must cover both payment data and administrative access. For card processing, PCI DSS responsibilities depend on the integration model; a hosted payment page can reduce exposure but does not automatically eliminate all institutional obligations. Privacy requirements, including GDPR where applicable, need separate attention to lawful processing, retention, international transfers, and processor contracts.
Operational controls are equally important: multifactor authentication, role-based access, dual approval for sensitive changes, and independent verification of settlement-account amendments. A secure checkout cannot compensate for an administrator account that allows an attacker to redirect funds.
Test the complete lifecycle before expanding coverage
A pilot should validate the whole journey, not merely a successful checkout. Use representative corridors and payment values to test quote expiry, settlement, ledger posting, missing references, refunds, and failed transactions. Where live testing is necessary, use controlled amounts and agreed procedures.
Measure outcomes that reveal infrastructure quality: net amount received against the invoice, elapsed time to usable funds, automatic matching rate, unresolved exceptions, and refund completion. Break results down by corridor and payment method; an aggregate average can conceal an unreliable route.
Service agreements should define settlement schedules, cutoff times, holiday treatment, incident escalation, reporting availability, and responsibilities when a partner fails. Keep a documented alternative collection route and retain exportable transaction data so that a provider outage or replacement does not sever the audit trail.
The strongest setup is not necessarily the one with the most payment buttons. It is the one that can explain every payment’s route, cost, legal handling, settlement status, and ledger treatment—and resolve an exception without asking the family to reconstruct the transaction from scratch.
Tags
Recommended for You
 OpenRouter Removes Three AI Inference Providers Over Prompt Theft RisksOpenRouter removes three AI inference providers over prompt theft risks and changes zero data retention eligibility for 125 endpoints. Explore what buyers need to know.Nov 22, 2026Lina Cloud
 FBI Database Suspected Breached; USDA Payment System Disrupted by CyberattackFBI database breach suspected as a USDA cyberattack disrupts farm payments. Explore the potential business impact and practical steps amid uncertainty.Nov 21, 2026Lina Cloud
 How to choose the right capacity for wholesale commercial planetary mixersPlanetary mixer wholesale commercial buyers: learn how to match capacity to recipes, compare supplier ratings, and choose the right mixer with confidence.Nov 21, 2026Lina Cloud
 European Commission Confirms AI-Enabled Cyberattack Took Applications OfflineEuropean Commission AI-enabled cyberattack took several applications offline. Discover what is known about the disruption, ARTEX and the ongoing investigation.Nov 20, 2026Lina Cloud
 When should OEMs conduct electromagnetic compatibility testing?Electromagnetic compatibility testing: OEM teams can reduce redesign risks by testing prototypes early and assessing release-ready products. Discover when to test.Nov 20, 2026Marcus Trust
 CISA Adds Four Vulnerabilities to Known Exploited Vulnerabilities CatalogCISA adds four vulnerabilities to its Known Exploited Vulnerabilities catalog. Discover what the listings mean for patch priorities and risk management.Nov 19, 2026Lina Cloud
 Can IP65 LED grow lights withstand routine washdowns?Can IP65 LED grow lights handle routine washdowns? Discover what the rating covers and how to clean fixtures safely without risking damage.Nov 19, 2026Marcus Trust
 Equinor Reports Cyberattack on IT Systems; Oil and Gas Production UnaffectedEquinor reports a cyberattack on its IT systems, with oil and gas production unaffected. Explore what the incident means for energy supply.Nov 18, 2026Lina Cloud
 How to assess integration capabilities when choosing AI kiosk suppliersCompare AI kiosk suppliers with a practical integration checklist covering APIs, payments, identity, peripherals, failure recovery, and support.Nov 18, 2026Dr. Hideo Tanaka
 US States and Cities Move to Ban Crypto Kiosks Amid Rising FraudUS crypto kiosk bans are gaining momentum amid rising fraud. Discover what local restrictions could mean for operators, suppliers and deployment plans.Nov 17, 2026Dr. Hideo Tanaka
 How many touch points does a classroom interactive panel need?Interactive panel touch points for classroom use: discover when 10 or 20 points make sense and how to choose a reliable display for student collaboration.Nov 17, 2026Professor Sarah Ed
 How to verify component distributors on a supplier discovery platformSupplier Discovery Platform tips for verifying component distributors: check authorization, traceability and delivery claims before you buy.Nov 16, 2026Lina Cloud
 Vietnam Health Ministry Orders Stronger Protection of HIV Patient InformationVietnam HIV patient privacy is in focus as the Health Ministry orders stronger data protection. Discover what the instruction means for healthcare providers.Nov 15, 2026Lina Cloud
 How long do Android smart terminals receive security updates?Android smart terminals have varying security update lifespans. Learn how to verify vendor commitments, assess remaining support, and plan a secure deployment.Nov 15, 2026Lina Cloud
 Microsoft 365 Consumer Services Restored After Global OutageMicrosoft 365 consumer services are back after a global outage. Discover what caused the disruption and why enterprise services remain under monitoring.Nov 14, 2026Lina Cloud
 How much does aeration add to aquaculture utility costs?Aquaculture utilities cost can rise significantly with aeration. Learn how to calculate energy expenses, compare equipment, and build a reliable budget.Nov 14, 2026Lina Cloud
 Trump AI Task Force Discusses Cyberattack Reporting Standards for Critical InfrastructureAI cyberattack reporting standards are under discussion for critical infrastructure. Explore potential impacts on operators, suppliers and incident response.Nov 13, 2026Lina Cloud
 How to check an EMC laboratory's test frequency rangeVerify an EMC test frequency range laboratory claim with confidence. Learn how to check accredited scope, test methods, facilities, and product requirements before booking.Nov 13, 2026Marcus Trust
 Singapore PDPC and CSA Issue Joint Advisory on Insecure API Data Protection RisksSingapore PDPC and CSA highlight insecure API data protection risks. Discover what developers and API users should know about security and compliance.Nov 12, 2026Lina Cloud
 How to size industrial coffee processing machinery for your production volumeSize industrial coffee processing machinery with confidence. Learn to calculate throughput, account for losses, and compare supplier capacity claims.Nov 12, 2026Lina Cloud
 Singapore CSA Issues Alert on Microsoft's November 2026 Security PatchesSingapore CSA’s November 2026 Microsoft security patch alert highlights potential risks. Explore what businesses should verify and how to plan updates.Nov 11, 2026Lina Cloud
 How many nits does a digital signage window display need?Explore digital signage brightness nits data for your window display, from shaded storefronts to direct sunlight, and choose a screen that stays readable.Nov 11, 2026Digital Signage
 CISA Adds SonicWall SonicOS MFA Bypass Flaw to KEV CatalogCISA adds the SonicWall SonicOS MFA bypass flaw, CVE-2026-19868, to its KEV catalog. Learn why it matters and what affected organizations should do next.Nov 10, 2026Lina Cloud
 Is a 50 kg spiral dough mixer right for your batch size?Is a 50 kg spiral dough mixer right for your bakery? Compare batch capacity, dough requirements and production timing before you buy.Nov 10, 2026Lina Cloud
 New Zealand NCSC Report Warns AI Is Accelerating CybercrimeNew Zealand's NCSC warns that AI is accelerating cybercrime. Discover what the report means for supply chain security and how organizations can respond.Nov 09, 2026Lina Cloud
 How to choose a touchscreen medical kiosk for patient check-inChoose a touchscreen medical kiosk with confidence. Explore accessibility, integration, privacy, cleaning and costs to find the right patient check-in solution.Nov 09, 2026Dr. Hideo Tanaka
 India’s DPDP Act and Rules Set New Compliance Demands for Schools and EdTechIndia’s DPDP Act and 2025 Rules raise data privacy questions for schools and EdTech. Explore consent, data minimization and practical review priorities.Nov 08, 2026Marcus Trust
 How much horsepower do commercial towable stump grinders need?Choosing towable stump grinders for commercial work? Compare horsepower ranges, cutting performance and towing limits to find the right machine for your workload.Nov 08, 2026Lina Cloud
 US Agencies Warn of Attacks Targeting Food and Medical Cold-Chain SystemsCold-chain cybersecurity is under scrutiny as US agencies warn of attacks on food and medical refrigeration controls. Explore the risks and practical steps to protect supplies.Nov 07, 2026Lina Cloud
 How to verify boric acid purity when buying wholesale from a factoryChoosing a wholesale boric acid factory? Learn how to verify purity, check batch COAs and plan independent tests before placing your order.Nov 07, 2026Marcus Trust
 Class A vs. Class B marine AIS transponders: Which do you need?Choose the right AIS transponder system marine applications demand. Compare Class A, Class B CSTDMA and SOTDMA, plus installation and compliance needs.Nov 06, 2026Lina Cloud
 OpenSSH 10.6p2 Fixes CVE-2026-123158 Password Authentication BypassOpenSSH 10.6p2 fixes CVE-2026-123158, a password authentication bypass. Find out which Linux systems are affected and how to secure them.Nov 06, 2026Lina Cloud
 Is a mini rice harvester for small farms worth the cost?Is a mini rice harvester for small farms worth the cost? Compare ownership expenses, payback, field suitability, and rental options before you invest.Nov 05, 2026Lina Cloud
 CISA Adds WordPress Core RCE Vulnerability to KEV CatalogWordPress core RCE vulnerability CVE-2026-119977 joins CISA's KEV catalog. Explore the active exploitation risk and what WordPress operators need to know.Nov 05, 2026Lina Cloud
 How to verify the EGCG content of 98% green tea extractGreen tea extract 98 EGCG: Learn how to verify purity with HPLC testing, assess COAs, compare reporting bases, and make confident quality decisions.Nov 04, 2026Marcus Trust
 European Supermarkets Hit by Second Wave of Smart Freezer CyberattacksEuropean supermarket cyberattacks target smart freezer controls, raising food safety concerns. Discover what happened and how retailers are responding.Nov 04, 2026Lina Cloud
 How do payment app encryption layers protect card data?Discover how payment app encryption layers protect card data in transit and at rest, and learn what to check when evaluating security and PCI DSS compliance.Nov 03, 2026Lina Cloud
 How to verify the purity of wholesale xylitol sweetenerVerify xylitol sweetener wholesale sugar substitute purity with batch-specific COAs, appropriate lab tests, and sampling practices that help reduce supply-chain risk.Nov 02, 2026Marcus Trust
 Thailand to Require Social Media Platforms to Verify Advertisers From November 1Thailand advertiser verification rules take effect November 1, 2026. Discover what social media platforms and businesses need to know before running paid ads.Nov 02, 2026Marcus Trust
 How does plant capacity affect blood meal processing plant cost?Blood meal processing plant cost depends on capacity, supply, and energy use. Compare plant sizes and uncover ways to improve your investment.Nov 01, 2026Lina Cloud